U.S. Inflation Jumps to 3.7% as Energy Shock Reaches American Consumers
U.S. inflation jumped to 3.7% in September, up from 3.4% in August, after gasoline prices surged 9.1% in a single month and accounted for more than half of the monthly increase.
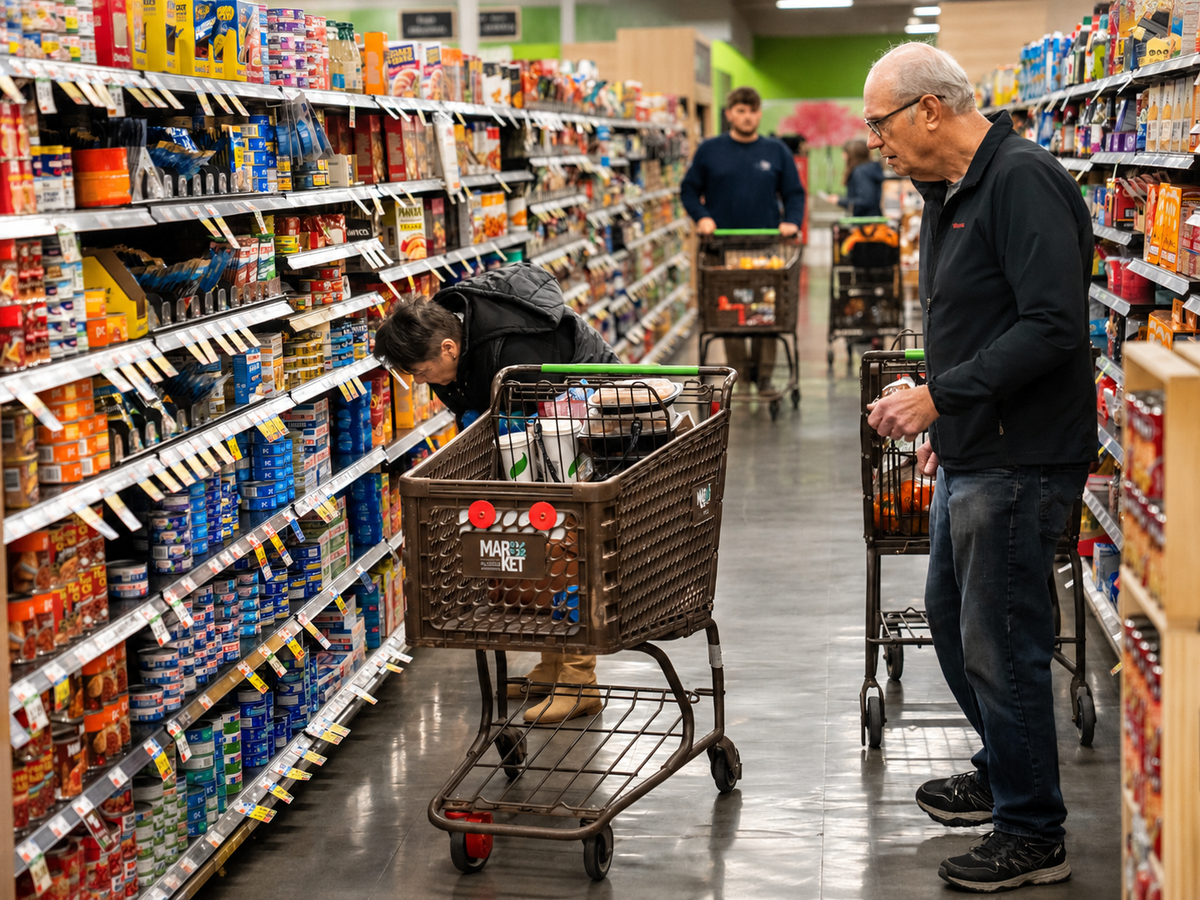
U.S. inflation accelerated sharply in September, reaching 3.7% as surging gasoline prices pushed consumer costs higher and complicated the Federal Reserve’s attempt to bring inflation back under control.
The Consumer Price Index rose 0.6% from August, the largest monthly increase in more than a year, according to the Bureau of Labor Statistics. Annual inflation climbed from 3.4% in August to 3.7% in September. Forex Factory
The biggest driver was energy.
Gasoline prices jumped 9.1% in a single month and accounted for more than half of the overall increase in the CPI. The spike reflects the disruption created by the Middle East war, attacks on energy infrastructure and shipping, and oil prices remaining above $100 a barrel. Forex Factory
That means the economic consequences of the conflict are now increasingly visible inside American households.
Higher oil prices do not stop at the gas pump.
They raise transportation costs, airline expenses, delivery prices, agricultural costs and the cost of moving almost every physical product through the economy.
Diesel is particularly important because it powers trucks, construction equipment, agriculture and large parts of the U.S. freight system.
The latest data therefore show how quickly a geopolitical energy shock can become domestic inflation.
But energy was not the only problem.
Core inflation, which excludes food and energy because of their volatility, rose 0.3% during September and 2.6% over the past year.
That figure remains substantially lower than headline inflation, but it was slightly hotter than economists had expected. Reuters
Prices also increased across categories including shelter, airfares and consumer goods.
That matters because the Federal Reserve can largely look through a temporary oil-price spike if underlying inflation remains contained.
It becomes much harder to do so if higher energy costs begin spreading into the rest of the economy.
Chicago Federal Reserve President Austan Goolsbee described the September inflation figures as “discouraging,” particularly because some of the pressure was appearing in services that cannot easily be blamed on oil or tariffs. Reuters
The report immediately changed expectations for interest rates.
The Federal Reserve had already raised its benchmark rate in September to a range of 3.75% to 4%, its first increase since 2023.
Before the latest CPI figures, another increase at the October 27 to 28 meeting appeared less likely.
That decision is now considerably less certain.
Markets moved toward roughly even odds of another rate increase following the report, although several Fed officials have since urged caution and indicated that one inflation reading may not be enough to justify immediate tightening. Reuters
The Fed’s problem is increasingly uncomfortable.
Inflation remains well above its 2% target.
But raising interest rates further would increase borrowing costs for mortgages, businesses, credit cards and the federal government.
Higher rates also increase the cost of servicing America’s already enormous national debt.
That places monetary policy directly inside the wider global debt problem currently dominating the IMF and World Bank meetings.
The U.S. government can tolerate high borrowing costs better than most countries because the dollar remains the world’s principal reserve currency.
But it is not immune.
As older government debt is refinanced at higher interest rates, a larger share of federal revenue has to be spent simply paying interest.
Inflation therefore leaves policymakers with two bad choices.
Keep rates elevated and place more pressure on borrowers and government finances.
Or cut rates too soon and risk allowing inflation to become entrenched again.
The September data make the second option more difficult.
There is also a political dimension.
The figures arrive less than three weeks before the November 3 midterm elections.
For American households, headline inflation matters far more than discussions about whether price increases originate from monetary policy, war or global supply chains.
Gasoline is one of the most visible prices in the economy.
Consumers see it every time they drive past a station.
Food, electricity and transportation costs are similarly difficult to ignore.
The Trump administration has been trying aggressively to reduce those pressures.
Washington recently reached an agreement allowing additional Russian diesel onto global markets despite sanctions imposed over the war in Ukraine.
The United States and other governments have also released emergency oil reserves as they attempt to increase supply and push prices lower.
Those decisions make more sense in light of the latest inflation report.
The administration is trying to prevent a temporary energy shock from becoming a broader cost-of-living problem.
But there are limits to what Washington can control.
Iranian attacks around the Strait of Hormuz continue to threaten one of the world’s most important energy corridors.
The Houthis have targeted Saudi airports and Aramco infrastructure.
Shipping costs and insurance premiums have risen sharply.
And any further escalation could push oil prices higher again.
That is why the September CPI report is about more than one bad month.
It demonstrates how exposed the U.S. economy remains to global energy markets.
Inflation had fallen to 2.4% at the beginning of 2026. Bureau of Labor Statistics
Eight months later, it is back at 3.7%.
The reversal does not mean America has returned to the inflation crisis of 2022.
Core inflation remains considerably lower than it was then, wage growth and employment conditions are different, and much of the latest acceleration is clearly linked to energy.
But the direction has changed.
Instead of continuing toward the Federal Reserve’s 2% target, inflation is moving away from it.
That creates a dangerous feedback loop.
Higher energy prices increase inflation.
Higher inflation keeps interest rates high.
High interest rates increase government and private borrowing costs.
And expensive borrowing slows investment precisely when governments are already carrying historically large debt burdens.
The United States remains one of the strongest major economies.
But September’s numbers are a reminder that even America cannot isolate itself from the economic consequences of a widening Middle East war.
The conflict is no longer only visible in missile strikes, shipping disruptions and oil markets.
It is now showing up in the price Americans pay for everyday life.