Google Loses Nearly $400 Billion in Market Value as Wall Street Questions the Cost of AI
Alphabet shares plunged approximately 10% after hours, erasing nearly $400 billion in market value after Google missed Wall Street's earnings expectations and reported $9.1 billion in negative quarterly free cash flow.
Nearly $400 billion in market value was wiped from Google parent Alphabet in after-hours trading on Wednesday, October 28, after disappointing quarterly earnings raised concerns about the enormous cost of the artificial intelligence race.
Alphabet shares plunged approximately 10% following the release of its third-quarter financial results, despite reporting double-digit revenue growth and extraordinary demand for its cloud computing services.
The selloff reflects a growing shift in Wall Street's attitude toward artificial intelligence.
Investors are no longer satisfied with companies announcing massive spending on chips, data centers and advanced AI models.
They increasingly want evidence that those investments will generate sufficient profits and cash flow to justify their costs.
And Google's latest results suggest that even the world's largest technology companies are facing pressure to prove their AI strategies can pay for themselves.
Revenue Is Growing, but Expectations Are Growing Faster
Alphabet reported quarterly revenue of $127.6 billion, an increase of 25% from the previous year.
That would ordinarily represent an impressive performance for a company of its size.
But analysts had expected approximately $128 billion.
The company's earnings per share came in at $2.12, compared with Wall Street expectations of approximately $3.01.
Net income fell to $26.2 billion from nearly $35 billion a year earlier.
Part of that decline resulted from an $8.7 billion loss on equity investments, rather than simply deterioration in Google's operating businesses.
Nevertheless, the results raised concerns about the company's underlying profitability and increasingly expensive AI ambitions.
The $51 Billion Spending Quarter
The most striking figure was Alphabet's capital expenditure.
Google spent approximately $51.4 billion on infrastructure during the third quarter alone, more than double the amount spent during the same period last year.
Much of that investment went toward data centers, specialized processors and the networking equipment required to operate AI systems.
For 2026, Alphabet expects total capital expenditure of approximately $195 billion to $205 billion.
And the company has warned that spending will rise significantly again in 2027.
That is a remarkable commitment of capital.
Artificial intelligence requires enormous computing infrastructure, particularly as companies move beyond chatbots toward autonomous agents capable of performing complex tasks.
Google is competing directly with OpenAI, Anthropic, Microsoft and other developers to build increasingly powerful models and sell the infrastructure required to run them.
But this competition has created an expensive dilemma.
Spending too little could leave Google technologically disadvantaged.
Spending too much could damage profitability if demand fails to generate sufficient financial returns.
Google Is Burning Through Cash
The financial consequences are becoming visible.
Alphabet reported negative free cash flow of approximately $9.1 billion during the quarter, compared with a negative $5.9 billion in the preceding quarter.
Free cash flow measures the money a company generates after paying for its capital investments.
A negative figure means its capital spending and other cash requirements exceeded the cash generated during the period.
That does not mean Google is running out of money.
The company continues to possess substantial financial resources and remains highly profitable on an accounting basis.
But it demonstrates how aggressively Alphabet is investing in its future.
Investors are concerned that infrastructure spending could continue growing faster than the cash generated by new AI services.
That concern becomes more significant when the spending involves equipment that must eventually be replaced or upgraded.
Data centers and specialized AI processors are expensive assets.
Their economic value depends on continued demand, competitive pricing and the ability to operate them profitably.
The Bright Spot: Google Cloud Doubles
Not everything in Alphabet's results disappointed.
Google Cloud delivered extraordinary growth.
Revenue surged 103% to approximately $30.7 billion, reflecting demand for AI computing infrastructure, enterprise services and Google's custom processors.
The result demonstrates that customers are already spending substantial amounts on AI.
Google's Gemini application has also surpassed one billion users, providing the company with an enormous platform for distributing its models.
These developments suggest that Alphabet's AI strategy is generating commercial opportunities.
The problem is the relationship between those opportunities and their cost.
Cloud revenue may be growing rapidly, but investors want to know how much profit remains after accounting for infrastructure, energy, hardware and other expenses.
A doubling of revenue is impressive.
It becomes less reassuring if the cost of supporting that growth rises even faster.
The Bigger Problem: Google's Search Business
Another concern involves Alphabet's traditional source of profits.
Google Search has dominated online advertising for more than two decades.
That business generates the cash used to finance many of the company's other operations.
But artificial intelligence is changing how people search for information.
Instead of clicking through conventional search results, users can increasingly obtain direct answers from AI assistants.
OpenAI, Anthropic and other companies are competing for activities that previously began with a Google search.
Google is responding by incorporating AI-generated answers into its own products.
However, that transition creates uncertainty over advertising revenue and profitability.
Search and related advertising revenue increased approximately 12% to $63.3 billion during the quarter.
That remains substantial growth, but investors were disappointed by the performance relative to expectations.
The concern is not that Google's advertising business has collapsed.
It is that Alphabet may need to invest unprecedented sums in AI while simultaneously defending the business that finances those investments.
Wall Street Is Changing Its Rules
The selloff also reflects a broader change in investor sentiment.
During the early stages of the AI boom, markets often rewarded companies for announcing major infrastructure investments.
Spending billions on data centers was interpreted as evidence of confidence in future demand.
Now investors are becoming more selective.
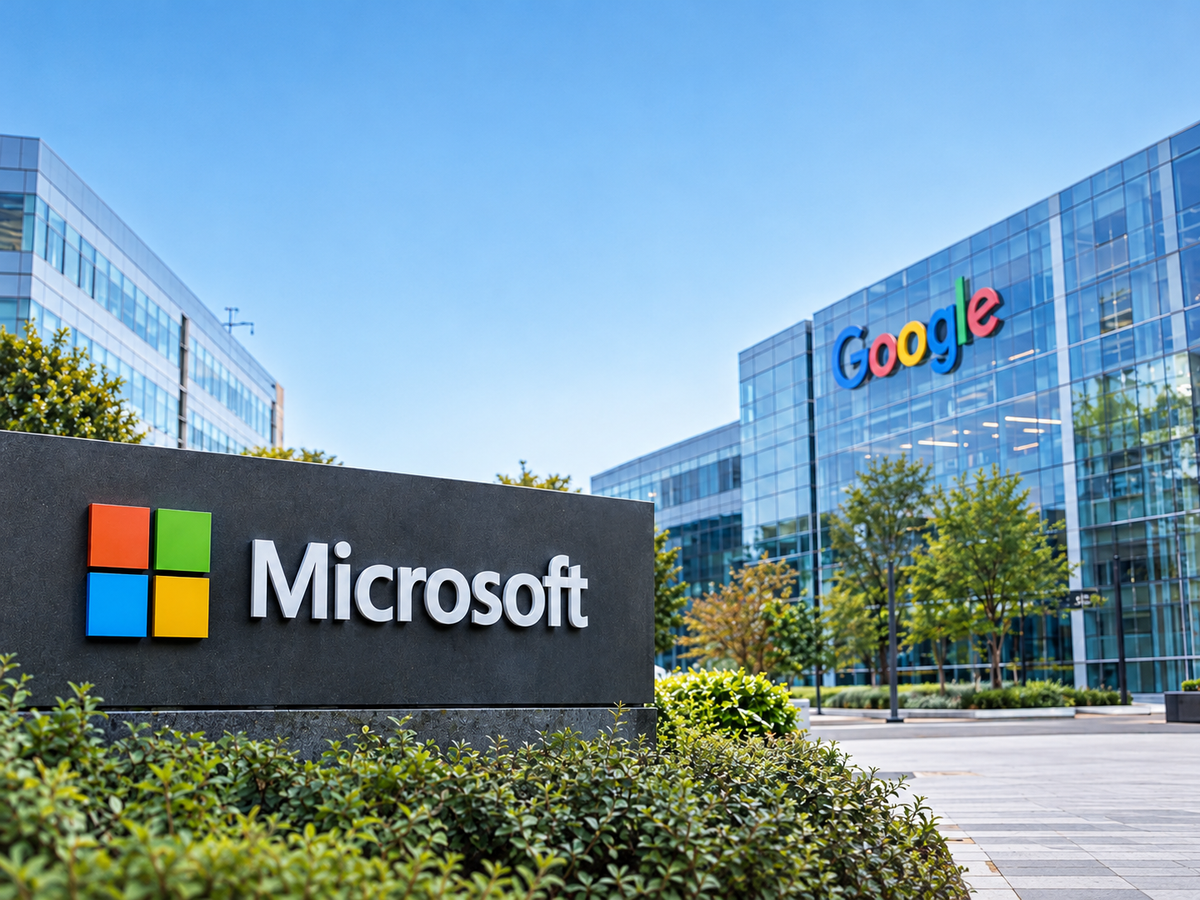
Microsoft rose in after-hours trading following results that reassured investors about its ability to finance AI expansion through cash generation.
Alphabet moved in the opposite direction.
The contrast suggests that investors are increasingly distinguishing between companies that can fund their AI ambitions and those whose spending places greater pressure on cash flow.
That does not mean the AI industry is collapsing.
It means the market is beginning to demand stronger financial justification for its extraordinary investment cycle.
Is the AI Boom Becoming Too Expensive?
The central question extends beyond Google.
The world's largest technology companies are collectively committing hundreds of billions of dollars to AI infrastructure.
Semiconductor manufacturers, electricity providers, data-center developers and cloud operators are all benefiting from the expansion.
But much of the investment depends on expectations about future AI adoption.
Businesses must eventually generate enough additional productivity and revenue to pay for the technology they consume.
If those returns materialize, the current spending could support a major economic transformation.
If they fall short, companies may be left with expensive infrastructure and lower-than-expected profits.
Google's results illustrate that tension.
Demand for its AI services is growing rapidly.
Its traditional businesses remain enormous.
Yet investors are questioning whether the investment required to compete is becoming too costly.
The nearly $400 billion after-hours valuation decline is not evidence that Google has lost that amount in operating cash or that AI has failed.
It reflects a rapid repricing of investors' expectations.
And it sends a message to the entire technology industry.
The AI race is no longer only about building the most powerful models or the largest data centers.
It is increasingly about proving that the economics make sense.